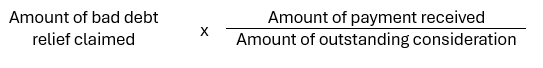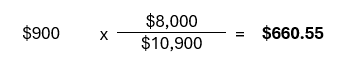
Bad Debt Relief (Checklist for Self-Review of Eligibility of Claim) (PDF, 221KB)
On this page:
What is bad debt relief
A bad debt arises when money owed by a customer cannot be recovered. As a GST‑registered supplier, you may claim bad debt relief to recover the output tax previously accounted for and paid to IRAS. You must claim within 5 years from the date of your supply.
Example:
- Date of tax invoice: 28 Jun 2023
- Final accounting period to claim bad debt relief: 1 Apr 2028 to 30 Jun 2028
Who can claim bad debt relief
You can claim if you meet all these conditions:
- You have supplied goods or services for a consideration in money and have accounted for and paid GST on the supply;
- You have written off the whole or any part of the consideration for the supply as a bad debt in your accounts;
- A period of 12 months beginning with the date of supply has elapsed or the debtor has become insolvent before the period of 12 months has elapsed;
- You have taken reasonable steps* to recover the debts;
- The value of the supply is equal to or less than its open market value; and
- In the case of goods, the ownership must have been transferred to your customer
*Reasonable steps means taking appropriate steps to recover the debt instead of simply writing it off as a bad debt. The steps undertaken may vary according to the size of the debt and the resources available to pursue the debt. Examples of debt-recovery actions include issuing reminder notices, attempting telephone, mail or email contact, and issuing a formal demand notice or summons. For more information, refer to paragraph 2 of the Explanatory Notes on Bad Debt Relief (Checklist for Self-Review of Eligibility of Claim) (PDF, 220KB).
How to claim bad debt relief
- Complete the Bad Debt Relief (Checklist for Self-Review of Eligibility of Claim) (PDF, 220KB).
- If you meet all conditions in the checklist, you can claim the relief by completing the following in your GST return:
- Box 7 (Input tax and refunds claimed): GST amount for the bad debt
- Box 11 (Bad debt relief claims): Select 'Yes' and enter the bad debt claim amount included in Box 7
- Keep the self-review checklist in your records. IRAS may ask for it during an audit.
If your customer pays you later
When you receive payment from your customer after claiming bad debt relief, you must repay IRAS the GST collected. Use this formula to calculate the amount to repay:
Amount to repay IRAS =
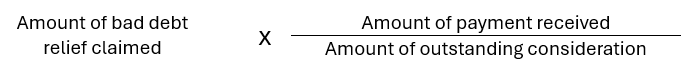
Note the following when applying this formula:
- The amount of outstanding consideration must include GST.
- The amount of payment received is taken as inclusive of GST.
GST Return: Include the amount to be repaid in Box 6 (output tax due)
You sold goods to Customer A and issued an invoice for $10,000 and $900 GST on 12 Mar 2024. You accounted for the output tax to IRAS in your GST return for the period ending 31 Mar 2024.
Customer A defaulted and you claimed $900 bad debt relief from IRAS, in your GST return for the period ending 30 Jun 2025.
Subsequently, Customer A pays you $8,000 on 15 Aug 2025. You are therefore required to repay IRAS part of your bad debt relief previously claimed. You should include the amount to be repaid in your GST return for the period ending 30 Sep 2025.
Amount to repay IRAS =